


The mortgage and property finance industry is increasingly making the case for drawdown products that let borrowers access funds as and when they need them, rather than taking a lump sum upfront. This flexible approach can be crucial for anyone who needs to act fast, whether it is completing a purchase before a competitor steps in or funding a renovation that will quickly lift a rental yield. The argument from specialist lenders is that waiting for a standard mortgage offer or a bridging loan avalanche can mean missing the moment entirely.
In its simplest form, flexible drawdown finance works like a pre-approved pot of cash that can be dipped into over time. Interest is charged only on the amount actually drawn, and repayments can often be sculpted around a project’s cash flow. For property investors, that might mean the deposit on a buy-to-let without disrupting other commitments, or funding a chain of small refurbishments one after the other. For those eyeing the lower end of the market, where outright purchase prices are smaller, the ability to draw exactly what is required can keep borrowing costs tidy.
Where affordability meets opportunity
| District | Post town | Region | Average price |
|---|---|---|---|
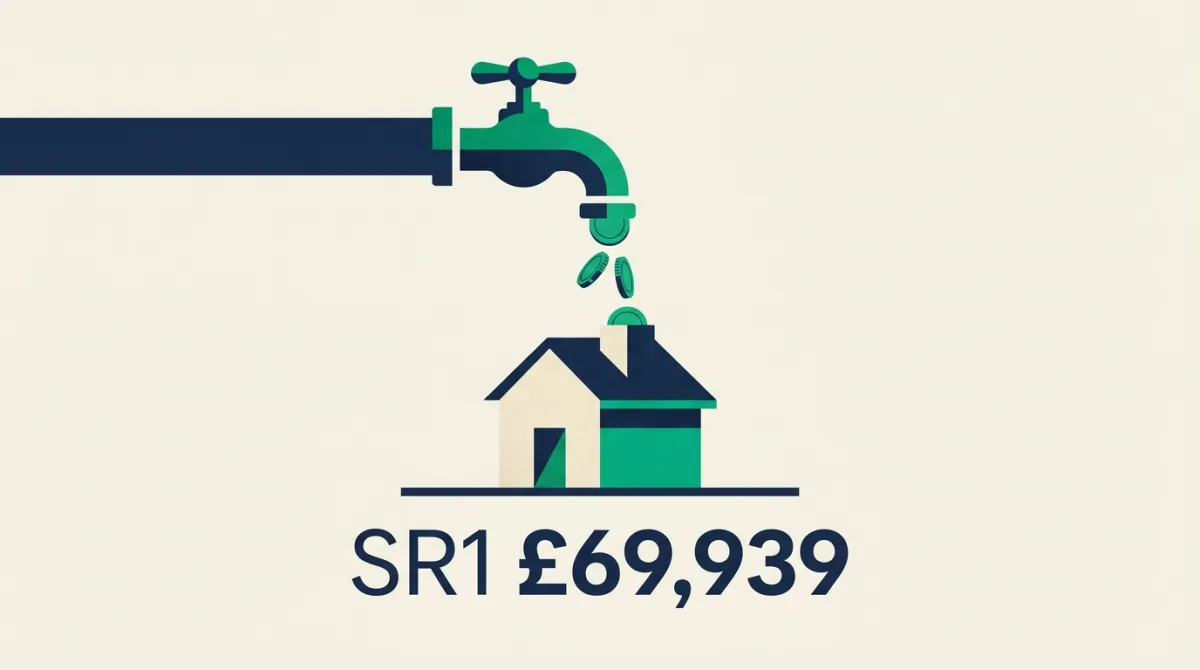
| SR1 | Sunderland | North East | £69,939 |
| DL4 | Shildon | North East | £79,214 |
| TS1 | Middlesbrough | North East | £80,533 |
| TS3 | Middlesbrough | North East | £82,642 |
| DN31 | Grimsby | Yorkshire and The Humber | £82,845 |
| HU2 | Hull | Yorkshire and The Humber | £86,318 |
| SR8 | Peterlee | North East | £89,506 |
| CF43 | Ferndale | Wales | £90,459 |
| BD1 | Bradford | Yorkshire and The Humber | £93,903 |
| DL17 | Ferryhill | North East | £98,478 |
Why SR1 in Sunderland stands out
The data held by Postcodes UK pinpoints one postcode district where the potential of flexible drawdown finance is most obvious: SR1, covering central Sunderland and its immediate riverside surrounds. With an average property price of just £69,939, this postcode district offers a rare foothold at a time when national averages sit many times higher. Someone using a drawdown facility could move quickly here, perhaps putting down a 25 per cent deposit of about £17,500 and keeping the rest of their agreed limit in reserve for refurbishment or a second purchase.
What makes the SR1 figure so compelling is not simply its sise but the breathing room it creates. A lower entry price means that even a modest drawdown line, arranged in advance, can cover the full acquisition cost if required. Investors who have secured a flexible finance line but have not yet used it can scan the market for properties listed near that average, confident that the numbers stack up without a prolonged application. In SR1, the gap between what is available and what a buyer can afford is narrow enough to be bridged by a single well-structured drawdown arrangement.
For developers and landlords, the surrounding rental market also matters. While SR1 itself is a compact urban district, it sits within a city that has seen steady tenant demand from students, university staff and those working in the expanding service sector. A property bought at the £69,939 average leaves substantial headroom between likely rental income and mortgage payments, a margin that can be further protected by drawing down only the exact funds needed, when they are needed. This is not about stockpiling cheap homes but about matching a modern funding tool to a price point where it works hardest.
The timing may be important too. As the wider cost-of-living and interest-rate environment gradually stabilises, doors open for buyers who have kept their powder dry. Flexible drawdown finance eliminates the scramble for a mortgage offer after spotting a deal; the commitment is already in place. In SR1, where properties can appear and disappear from the market quickly, that speed can translate directly into a successful purchase.
The data behind this
The figures discussed are drawn from the Postcodes UK database, which combines transaction records from HM Land Registry with demographic and economic indicators from the ONS census and other official releases. Our analysis focuses on SR1 as the cheapest postcode district captured in the latest data snapshot, with an average property price of £69,939. This average is based on completed sales registered by HM Land Registry and may include a mix of flats, terraced houses and other dwelling types. For the most up-to-date breakdowns by property type and for neighbouring postcodes, readers can explore the Postcodes UK site directly.
In response to reporting by Mortgage Solutions. Analysis and figures by Postcodes UK.